Personal Finance Tips by Life Stage: A 2026 Money Roadmap
Generic advice fails because money needs change with age. The smartest personal finance tips for 2026 are the ones matched to your life stage, since a 25-year-old paying off student loans and a 50-year-old eyeing retirement face completely different trade-offs. This roadmap walks you decade by decade so you always know your next move.
Think of your financial life as a relay race. Each decade hands the baton to the next, and the habits you set early decide how fast you can run later. Let us map the route.
Your 20s: Build the Foundation
Your twenties are about laying rails, not getting rich. Income is often low, but time is your greatest asset. A dollar invested now outperforms the same dollar invested in your forties by a wide margin thanks to compounding.
Focus on three foundations: an emergency fund, a clean credit history, and the saving habit itself. The amount matters less than the routine. Even a tiny automated transfer trains the muscle you will rely on for life.
- Open a high-yield savings account and automate deposits.
- Use credit cards for convenience, never as extra income.
- Start retirement contributions early, even at 5% of pay.
- Invest in skills that raise your earning ceiling.
The U.S. government’s MyMoney resource offers free, unbiased guides on credit and saving basics, a smart first stop before you trust any influencer.
Your 30s: Accelerate and Protect
The thirties usually bring higher income alongside bigger responsibilities: a mortgage, children, or aging parents. This is the decade to accelerate wealth while protecting what you have built.
Balancing Growth and Safety
Raise your savings rate with every promotion and resist lifestyle creep, the silent wealth killer that expands spending to match each raise. Lock in insurance while it is cheap, and write a basic will if you have dependents.
Practical personal finance tips for this stage centre on automation and insurance, because your time is now split across far more demands than it was a decade earlier.
Your 40s and Beyond: Optimise for Retirement
By your forties, the focus shifts from building to optimising. Earnings often peak, so this is the window to maximise retirement contributions and clear any remaining high-interest debt before it follows you into retirement.
Run a retirement projection to see whether your current pace meets your target. If there is a gap, closing it now is far easier than at 60. Review asset allocation too, gradually tilting toward stability as your horizon shortens.
Money Priorities at a Glance
| Life Stage | Top Priority | Common Mistake |
|---|---|---|
| 20s | Start saving and investing early | Waiting for a “better” salary |
| 30s | Protect income and accelerate | Lifestyle creep |
| 40s | Maximise retirement savings | Ignoring the projection gap |
| 50s+ | Preserve and plan withdrawals | Taking on new debt |
Tools That Work at Every Age
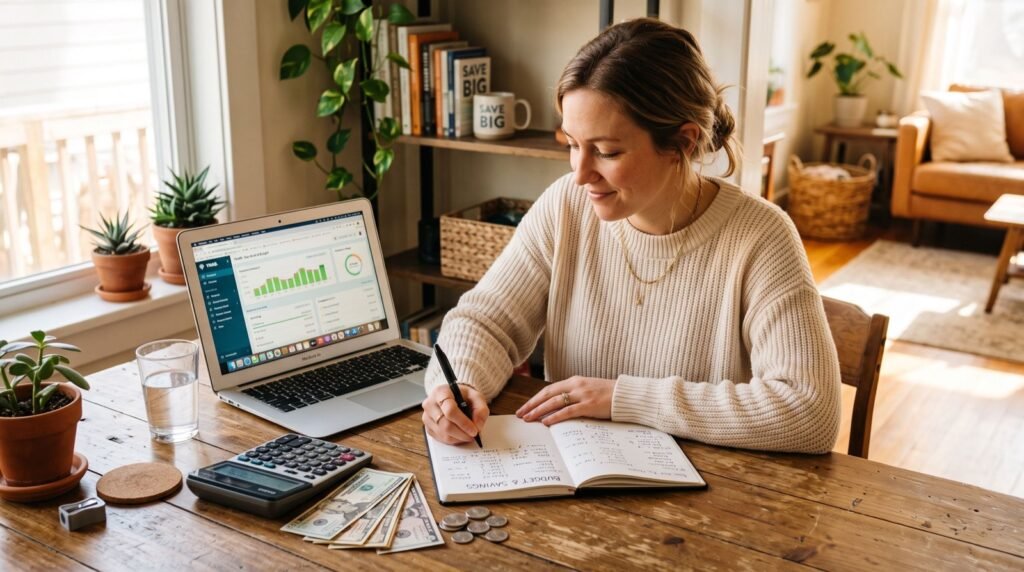
Whatever your decade, technology removes the friction that derails good intentions. Linking your accounts to a single dashboard makes patterns visible and keeps automation running on autopilot.
The best money apps now adapt to your stage, nudging a 25-year-old to build an emergency fund while prompting a 45-year-old to top up retirement accounts before the tax-year deadline.
A Simple Setup Routine
- Connect every account to one budgeting dashboard.
- Automate transfers for saving and bills.
- Set one calendar reminder each quarter to review progress.
- Rebalance investments once a year, not once a week.
An Original Insight: The Decade Buffer
Here is a tip rarely spelled out: always save as if your next life stage will arrive a decade early. Build your emergency fund in your twenties as though a mortgage is coming in your thirties; fund retirement in your thirties as though you will retire in your fifties. Pulling each goal forward by ten years turns last-minute panic into calm, early readiness.
For complex situations such as business ownership or inheritance, a conversation with dependable specialists can keep your personal and professional finances cleanly structured as they grow.
Common Money Mistakes at Every Age
Some errors are universal, striking people in every decade. Spotting them early is half the battle, because awareness alone often prevents the slip.
The first is neglecting an emergency fund. Without a cash cushion, a single car repair or medical bill becomes credit-card debt that lingers for years. The second is paying only the minimum on cards, which quietly doubles the real cost of a purchase through compounding interest working against you.
The third is lifestyle inflation, where every raise is immediately spent rather than partly saved. And the fourth is waiting for the “perfect” moment to start investing, a moment that never arrives. Beginning imperfectly today beats waiting flawlessly forever.
- No emergency fund to absorb surprises.
- Minimum-only credit card payments.
- Spending every raise instead of saving part of it.
- Delaying investing while waiting for perfect conditions.
Review Your Plan Once a Year
A financial roadmap is not a set-and-forget document. Life changes, and your plan should change with it. Schedule one honest annual review, ideally around your birthday or the new year, to check progress and reset goals.
During the review, confirm your savings rate still matches your income, update beneficiaries after any major life event, and rebalance investments that have drifted from your target mix. This yearly habit keeps small gaps from quietly becoming large ones.
Frequently Asked Questions
What personal finance tips matter most in your 20s?
Start saving and investing immediately, even in small amounts, and protect your credit score. Compounding rewards early starters enormously, so the habit you build at 22 is worth more than a larger effort delayed to your thirties.
How do I avoid lifestyle creep in my 30s?
Automatically route a share of every raise or bonus to savings before it reaches your spending account. If the extra money never lands in your checking balance, you will not build habits around spending it.
Is it too late to start investing in my 40s?
No. While earlier is better, your forties often bring peak earnings, letting you contribute aggressively. Maximise tax-advantaged retirement accounts and run a projection so you know exactly how much to set aside each month.
Which money app suits every life stage?
Choose one that combines budgeting, automated saving, and investing with strong security. The ideal app grows with you, adjusting its prompts as your priorities shift from building wealth to preserving it.
Final Word
The strongest personal finance tips meet you where you are. Build foundations in your twenties, accelerate and protect in your thirties, and optimise for retirement from your forties on. Match your habits to your stage, lean on smart tools, and stay one decade ahead. Do that and every handoff in your money relay lands smoothly.